The policy a lot of river-country homes don't have. Yet.
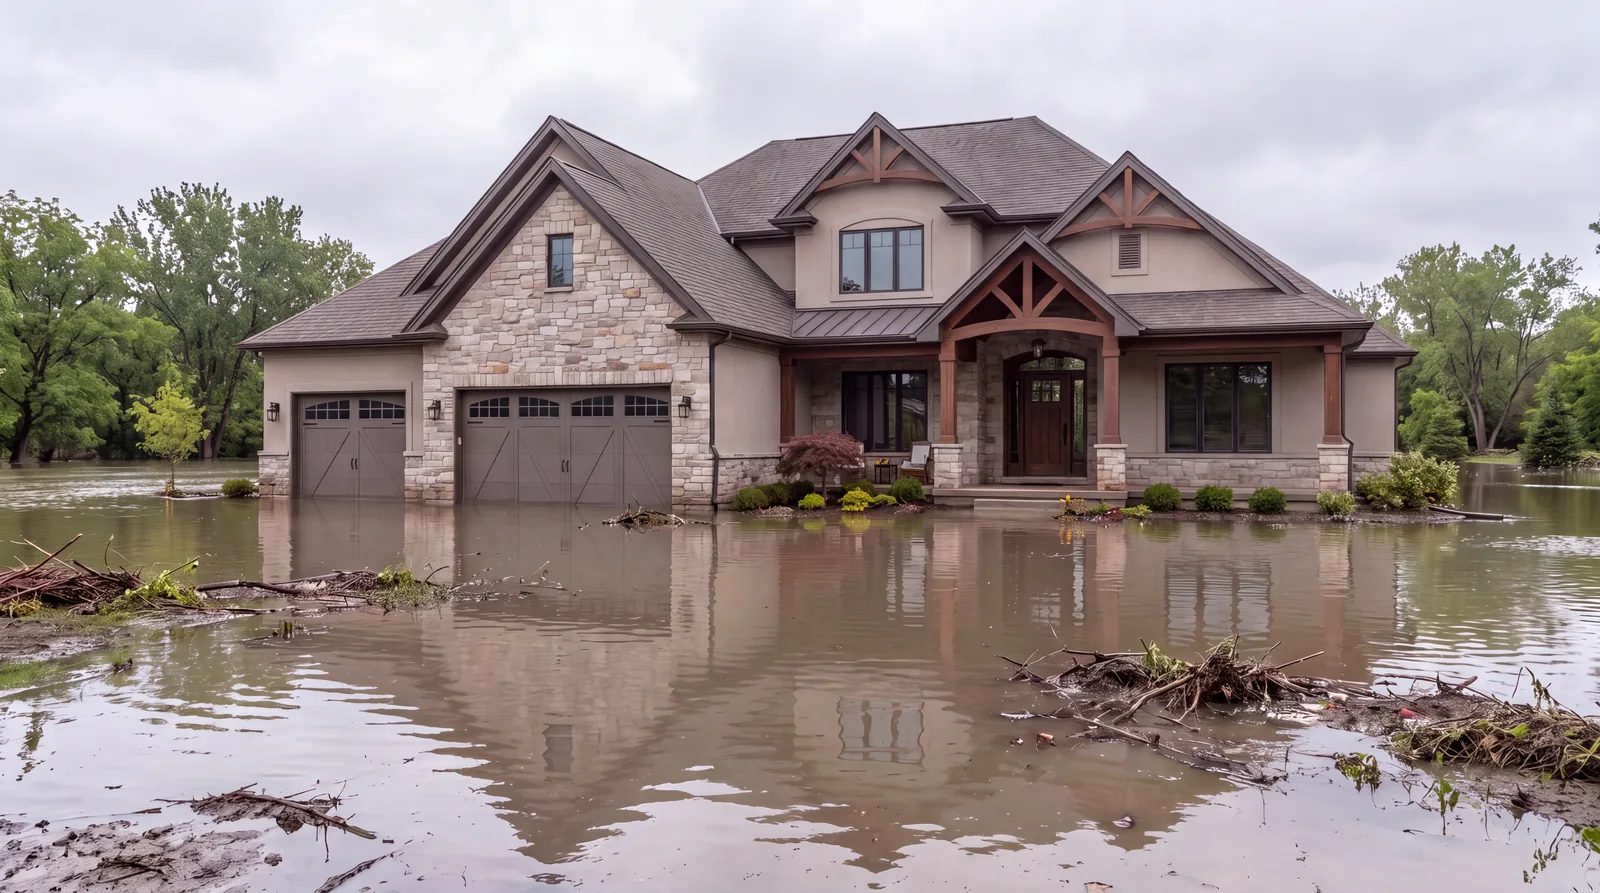
Here's the part that surprises almost everyone, so we'll put it first: your homeowners policy doesn't cover flood damage. Rising water and overflow from rivers, creeks and overwhelmed drainage are excluded from standard home and renters policies. It doesn't matter how long you've had the policy. Flood coverage is its own policy, usually written through the federal National Flood Insurance Program (NFIP).
The second thing to know is that it has happened here, more than once. The Meramec and Bourbeuse rivers flooded to record levels in December 2015, and again in May 2017, when record flooding was forecast on the Meramec near Sullivan. Lenders only require flood insurance in high-risk zones, but the zone that triggers the mandate and the water that reaches your house don't always line up.
The third thing is the basement. A lot of "flooded basement" calls aren't flood claims at all. If water comes up through a floor drain because the sewer backed up, or because the sump pump failed, that's a water backup loss. It's handled by your homeowners policy, and only if you added a water backup endorsement. We'll help you check both.
That's the offer. We explain the coverages to you and let you pick what works for you. We'll help you look up your flood zone, explain NFIP coverage and any private flood options that may be available, size the building and contents limits to your actual house, and show you how flood fits next to your home and auto coverage. Call (573) 358-4513.