Home / Sullivan, Missouri

Your Sullivan insurance agency, right on Dunsford Drive.

We're a Farmers agency with more than one door. We actually explain the coverages to you and let you pick what works for you, whether that's Farmers or another option through Kraft Lake.

SullivanLocal office
52Client reviews
4Hometown team
Mon–Fri9 AM to 5 PM Central
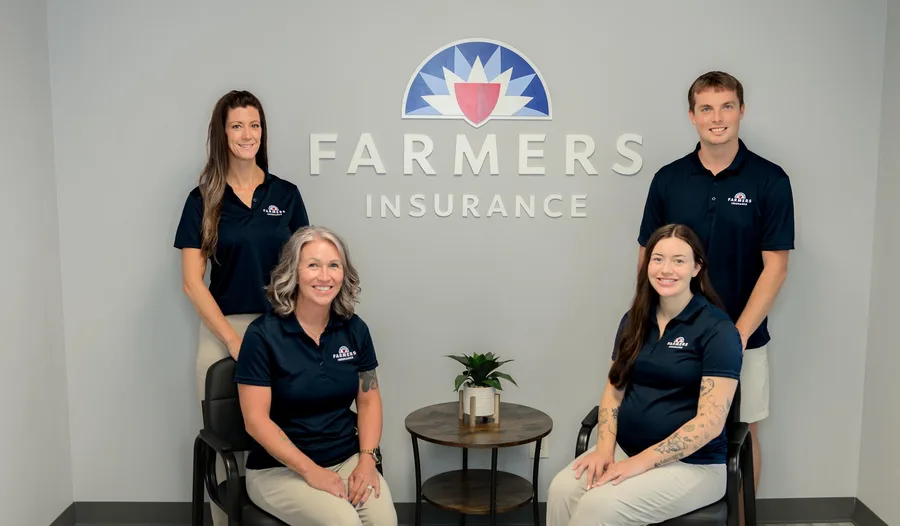
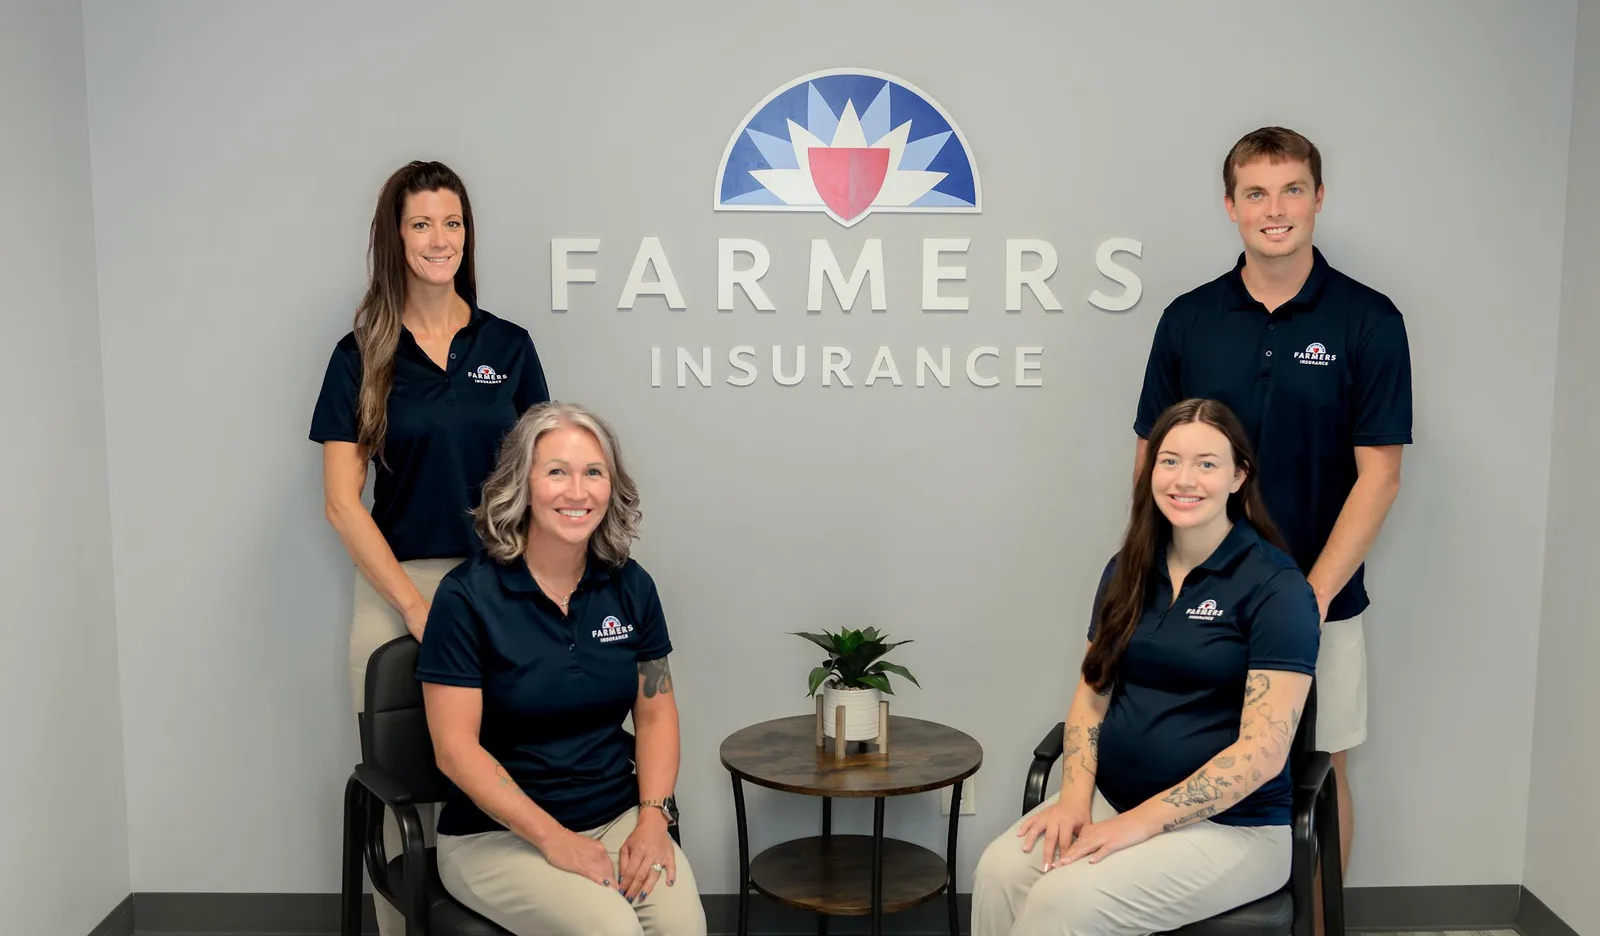
Tina Gregory and her team in the Sullivan, Missouri office
The Quick Answer

Tina Gregory Agency is a Farmers Insurance agency at 878 Dunsford Dr in Sullivan, Missouri, open Monday to Friday, 9:00 AM to 5:00 PM Central. Owner Tina Gregory leads a local team of four that helps families and businesses in Sullivan and nearby towns in Franklin and Crawford counties. Farmers comes first. When Farmers isn't the best fit, we can also quote companies like Farmers family companies Foremost and Bristol West, or outside companies like Progressive and Liberty Mutual through Kraft Lake Insurance Agency. We explain the coverages in plain English and let you pick. Sullivan-area homeowners should know their wind and hail deductible and ask about a separate flood policy near the Meramec and Bourbeuse rivers. Missouri's auto minimum is 25/50/25, plus required uninsured motorist coverage. We have 52 client reviews across Google and our Farmers page. Call (573) 358-4513.

Office
878 Dunsford Dr, Sullivan, MO 63080
Hours
Mon–Fri, 9:00 AM – 5:00 PM Central
Reviews
52 across Google and our Farmers page
Free quotes
(573) 358-4513

Visit the Sullivan office. Or just call.

Our office is at 878 Dunsford Dr in Sullivan. Stop in, call or email. Most quotes can be handled by phone, and we're glad to sit down in person when that's easier.

Address
Sullivan

878 Dunsford Dr

Sullivan, MO 63080
Open in Google Maps · Get directions

Phone & email

Call or email us

tgregory1@farmersagent.com
Quotes, questions and policy reviews all start here.

Hours
Mon–Fri

9:00 AM – 5:00 PM Central

Already a client? Visit the Service Center for help with an existing policy.

Sullivan Roots

We live here too. So does our team.

Sullivan sits on the Franklin and Crawford county line, where I-44 meets MO-185 and historic Route 66 still runs through town. It's a small city, about 6,900 people as of the 2020 census, with Meramec State Park just down the road. It's home, and it's where our office is.

Our team of four is local. Tina Gregory owns the agency. Matthew Tolliver, one of our insurance agents, was born and raised in Sullivan. Kathleen Orick has lived in Sullivan for 10 years and also teaches locally. Maggie Gregory, our office coordinator, keeps things running behind the scenes. Meet the team.

Here's how we work. We actually explain the coverages to you and let you pick what works for you. We're a Farmers agency first. When Farmers isn't the best fit, we can also quote Farmers family companies like Foremost and Bristol West, or other companies like Progressive and Liberty Mutual through Kraft Lake Insurance Agency. No pressure either way. More about Tina.

Coverage we write for Sullivan families and businesses. Farmers first, other options when it fits.

Personal and business coverage, explained in plain English. Not every product is available from every company, so we'll tell you what fits. Pick a line to learn more, or request a quote for anything below.

Already insured? Let's look at what you have.

Bring in your declarations pages or email them over. We'll walk through your limits, deductibles and the add-ons Sullivan-area homes tend to need, in plain English. No pressure either way.

Insuring a Sullivan-Area Home and Family

What we look at first around Sullivan. Hail, high water and the road.

Every policy is different, but the same few questions come up again and again with clients around Sullivan. Here's how we think about them.

Hail, wind and spring storms

Spring and summer storms bring hail, high winds and, some years, tornadoes. Wind and hail are typically covered on a homeowners policy, subject to your deductible. The Missouri Department of Commerce and Insurance notes that some insurers use a percentage deductible for wind and hail. At 2% of a $100,000 dwelling limit, that's $2,000 out of pocket. We'll show you your number before storm season.

Flooding on the Meramec and Bourbeuse

Both rivers flooded to record levels in December 2015 and again in May 2017, when record flooding was forecast on the Meramec near Sullivan. Standard home and renters policies exclude flood. A flood policy is a separate purchase, and NFIP policies generally have a 30-day waiting period. Sullivan participates in the NFIP, and private flood may also be available. Check your flood zone instead of assuming.

Basements, water backup and sinkholes

Water that backs up through a drain, or overflows when a sump pump fails, is usually excluded from a standard homeowners policy unless you add a water backup endorsement. The same goes for condo and renters policies. Missouri also has about 16,000 identified sinkholes, according to the Missouri Department of Natural Resources. Standard policies typically exclude earth movement, but sinkhole coverage may be available by endorsement or through the Missouri FAIR Plan.

Driving I-44, MO-185 and the back roads

Missouri's auto minimum is 25/50/25: $25,000 of bodily injury coverage per person, $50,000 per accident and $25,000 of property damage. Missouri also requires uninsured motorist coverage at $25,000/$50,000. Underinsured motorist and medical payments coverage are optional, and Missouri is an at-fault state. Deer are a common sight on rural roads around here, especially around dawn and dusk. Hitting a deer is generally a comprehensive claim, not collision, so it's worth checking that your auto policy includes it. If you have a home and assets to protect, an umbrella policy adds another layer on top.

Sullivan businesses and rental owners

From main-street shops to contractors to the rental house down the road, we write business insurance and landlord coverage too. In Missouri, workers' comp is generally required for most employers with five or more employees, and for construction businesses with one or more. We can help you figure out where you stand.

Also serving. Sullivan and the I-44 corridor.

From our Sullivan office, we work with families and businesses across Franklin and Crawford counties and nearby towns along I-44. We're licensed in Missouri, so we can help wherever you live in the state.

Why clients stick with us. 52 reviews across Google and Farmers.

Client reviews
52

Across Google and our Farmers page

Read what clients say after working with Tina and her team, in their own words, on Google and on our Farmers agent page.

How we work

We explain, you pick

We actually explain the coverages to you and let you pick what works for you. Plain English, no pressure.

Local team

Four people, one office

Tina, Matthew, Kathleen and Maggie, all working out of our Sullivan office on Dunsford Drive.

Sullivan insurance questions. Straight answers.

Where is your Sullivan office, and when are you open?

Our office is at 878 Dunsford Dr, Sullivan, MO 63080. We're open Monday through Friday, 9:00 AM to 5:00 PM Central.

You can call (573) 358-4513 or email tgregory1@farmersagent.com. Most quotes can be handled by phone or email, and we're happy to meet in person when you'd rather sit down.

Can you quote companies other than Farmers?

Yes. We're a Farmers Insurance agency, so Farmers is our main company. When Farmers isn't the right fit, we can also quote Farmers family companies like Foremost and Bristol West, or outside companies like Progressive and Liberty Mutual through Kraft Lake Insurance Agency.

Either way, we actually explain the coverages to you and let you pick what works for you. Not every product is available from every company, and we'll tell you what fits.

What are the minimum auto insurance requirements in Missouri?

Missouri requires liability limits of at least 25/50/25: $25,000 for bodily injury per person, $50,000 per accident and $25,000 for property damage. Missouri also requires uninsured motorist coverage at $25,000/$50,000.

Underinsured motorist and medical payments coverage are optional, and there's no PIP requirement. Missouri is an at-fault state. The minimum can run out quickly after a serious crash, so we'll show you what higher limits may cost. If your car is financed or leased, your lender will usually require collision and comprehensive too.

Does homeowners insurance cover flooding from the Meramec or Bourbeuse?

No. Water that rises from outside, like a river or creek over its banks, is flood, and standard home and renters policies exclude it. Both rivers flooded to record levels in December 2015 and May 2017.

Flood coverage is a separate policy, often through the National Flood Insurance Program (NFIP), and Sullivan participates in the NFIP. NFIP policies generally have a 30-day waiting period, so buy before the forecast turns. If you have a mortgage on a home in a high-risk flood zone, your lender will require it. Private flood may also be available.

How do wind and hail deductibles work in Missouri?

Many policies use a flat dollar deductible, but the Missouri Department of Commerce and Insurance notes that some insurers use a percentage deductible for wind and hail. A 2% deductible on a $100,000 dwelling limit means you'd pay the first $2,000 of a covered wind or hail claim.

We'll show you which kind your policy has and what it would mean in dollars before storm season, not after.

Is hitting a deer covered by car insurance?

Generally, yes, if you carry comprehensive coverage. A collision with a deer is usually handled under comprehensive, not collision, subject to your deductible. Liability-only policies won't pay for damage to your own car.

Deer are common on rural roads around Sullivan, so it's worth checking your policy. Call us and we'll walk through what you have.

I rent or own a condo in Sullivan. What coverage do I need?

Renters insurance covers your belongings, your personal liability and extra living costs if the place becomes unlivable. Missouri law doesn't require it, but a landlord can require it in your lease. Your landlord's policy covers the building, not your things.

Condo owners need a unit-owner (HO-6) policy that fills the gaps between you and the association's master policy, usually including interior finishes and loss assessment. On both, ask about a water backup endorsement.

Do you insure Sullivan businesses and rental properties?

Yes. We write business insurance for local shops, contractors and offices, plus landlord coverage for homes and small rental properties you rent to others.

In Missouri, workers' comp is generally required for most employers with five or more employees, and for construction businesses with one or more. We can help you figure out where you stand and coordinate it with the rest of your coverage.

Still have questions? Call (573) 358-4513. We'll give you a straight answer.

Your Sullivan agency, right on Dunsford Drive.
Free, local and in plain English.

Call, stop by the office or start a quote online. We'll explain the coverages and let you pick what works for you.