By clicking Get My Free Quote, I give Tina Gregory Agency (Tina Gregory Insurance Agency LLC) and its licensed agents, and, for quotes from insurance companies other than Farmers, Kraft Lake Insurance Agency, my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (573) 358-4513 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Maybe you just closed on a house off MO-185, or your renewal came in higher and you want to know what drives the costs and what your coverage really includes. Or a spring storm just rolled through, and you’re reading your policy for the first time.
Insuring a home around Sullivan comes with its own questions. The city straddles the Franklin and Crawford county line, with 6,906 residents at the 2020 census. Some homes sit near the Meramec or the Bourbeuse, some on acreage with a shop out back, and the whole area gets spring hail. This guide covers what a policy covers and leaves out, what moves the price and how our office puts a quote together. For the statewide picture, start with our Missouri homeowners insurance guide.
What does a homeowners policy cover for a Sullivan home?
The short answer: A standard policy covers the house, other structures, your belongings, extra living costs and your liability, but flood, earthquake and earth movement are left out, and sewer backup usually needs an add-on.
A standard homeowners policy, often called an HO-3, covers the dwelling, other structures, personal property, loss of use, personal liability and medical payments to guests, for sudden losses like wind, hail and fire, subject to your deductible and terms.
The Missouri Department of Commerce and Insurance (DCI) consumer guide lists flood and earthquake under what isn’t covered. Here’s how the common Sullivan-area risks sort out:
| Risk | Standard policy? | What to ask |
|---|---|---|
| Wind, hail and fire | Usually covered | Is the wind and hail deductible a flat amount or a percentage? |
| Sewer or sump pump backup | Add-on | A water backup endorsement, with a limit you choose. |
| Flood (rising water) | Separate policy | NFIP or private flood; NFIP generally waits 30 days. |
| Sinkholes, earthquake | Usually excluded | An endorsement or separate policy where available. |
The number that matters most is your dwelling limit. Market value counts the lot and leaves out debris removal and today’s building codes, so rebuild cost can land far from the sale price.
Sinkholes. Missouri is karst country: the Department of Natural Resources counts about 16,000 known sinkholes statewide. Standard policies typically exclude earth movement. Sinkhole coverage may be available by endorsement, and on March 4, 2015, DCI announced that Missourians can buy a standalone Sinkhole Loss policy through the Missouri FAIR Plan.
What if your home sits on acreage with a shop, barn or well?
The short answer: Detached buildings fall under other structures coverage, often set as a share of the dwelling limit, so tell us about every shop, barn and outbuilding.
Other structures coverage pays for a detached garage, shed, fence or pole barn. Many policies set it as a percentage of the dwelling limit. Check yours on the declarations page: if it were 10% on a home insured for $200,000, that’s $20,000 for everything detached.
Questions worth bringing to the quote:
- What would each outbuilding cost to replace? Size and construction matter.
- Is anything used for a business or farming? That may need different coverage, so tell us up front.
- Are you on a well? Ask how your policy treats the pump and a separate well house.
How do hail and wind deductibles work on a Sullivan home?
The short answer: Wind and hail are usually covered, but some insurers use a percentage deductible for them, figured on your dwelling limit, so turn it into dollars before storm season.
Spring brings hail, high wind and, some years, tornado warnings. Those losses are usually covered; the deductible is the part people miss. DCI’s guide to lowering your premium notes that “some insurance companies sell homeowners insurance policies with percentage deductibles for wind and hail damage.” DCI’s example is a house insured for $100,000 with a 2 percent deductible, where $2,000 comes off the claim.
- A kitchen fire claim: you pay the first $1,000.
- A hail claim for a new roof: you pay the first $5,000, because 2% of $250,000 is $5,000.
Also ask whether your roof settles at replacement cost or actual cash value, which reduces the payment for the roof’s age. Our Missouri storm, flood and sinkhole playbook goes deeper on storm season.
Do Sullivan homeowners need flood insurance?
The short answer: Homeowners policies exclude flood, Sullivan participates in the National Flood Insurance Program, and a new NFIP policy generally takes 30 days to start, so look up your address and decide before the river rises.
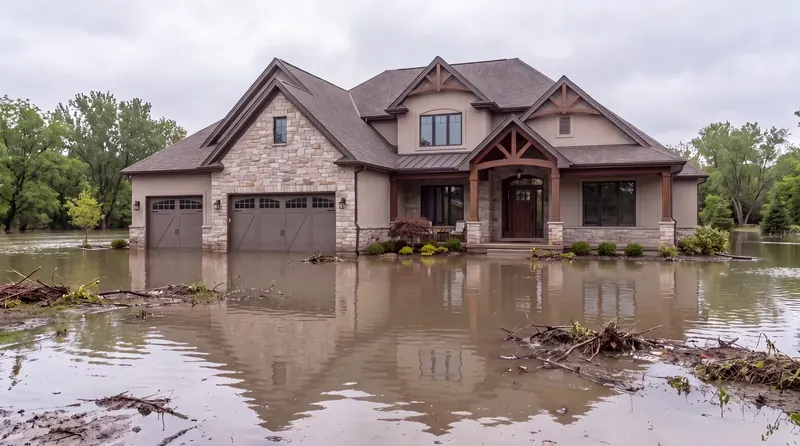
Rising water from the Meramec, the Bourbeuse or a creek isn’t covered by a home policy. And the water has come up before. The National Weather Service in St. Louis called the December 2015 flood “the new benchmark for river flooding along the Bourbeuse and Meramec River Basins,” with the Bourbeuse at Union cresting at a record 34.31 feet on December 29, 2015. In a flood warning issued the night of April 30, 2017, NWS forecast record flooding on the Meramec near Sullivan, and its spring 2017 summary notes at least four gauges set record crests.
- Sullivan participates in the NFIP. FEMA’s Community Status Book lists the City of Sullivan (community 290136, in Crawford and Franklin counties) as participating in the regular program since June 15, 1981, with no sanction (data as of August 25, 2026).
- The current flood map dates to October 18, 2011, per the same FEMA record. Look up your own address on FEMA’s Flood Map Service Center.
- There’s a waiting period. FEMA says “typically, there’s a 30-day waiting period from date of purchase before your policy goes into effect,” with limited exceptions.
- Lenders require it in high-risk zones. FEMA says that with a government-backed mortgage on a home in a Special Flood Hazard Area, flood coverage is required. Elsewhere it’s your call, and private flood may be available.
By clicking Get My Free Quote, I give Tina Gregory Agency (Tina Gregory Insurance Agency LLC) and its licensed agents, and, for quotes from insurance companies other than Farmers, Kraft Lake Insurance Agency, my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (573) 358-4513 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
What drives the price of home insurance in Sullivan?
The short answer: Rebuild cost, the roof, age and updates, fire protection, claims history and your deductibles drive it, not a town average.
There isn’t a reliable public average premium for one small city, and two houses on the same road can price very differently. Here’s what moves the number:
Rebuild cost
Your dwelling limit is the base most of the premium is built on.
Roof age and material
An older roof can raise the price or change how a roof claim is settled.
Fire protection
Most insurers use a 1-to-10 grade of local fire protection, and it feeds into the price.
Age, updates and claims
Documented wiring, plumbing and heating updates help; past claims can raise the price.
Deductibles and add-ons
DCI notes that a higher deductible generally means a lower premium.
Fire protection is the local one. Verisk, which runs the Public Protection Classification program, says virtually all U.S. home insurers use its 1-to-10 classes in calculating premiums, and that Class 1 generally represents superior fire protection. Around Sullivan, that’s usually the Sullivan Fire Protection District, which serves parts of Franklin, Crawford and Washington counties and lists its stations on its own website. Out on acreage, distance to a station and a hydrant can rate differently than in town. We check what applies to your address when we quote.
Discounts. DCI notes discounts for safety features like smoke detectors, burglar alarms and dead-bolt locks. You may also qualify for bundling or occupation discounts. Eligibility varies, and discounts aren’t available in every situation.
What if you’re non-renewed or can’t find home coverage?
The short answer: Call us when the letter arrives: we start with Farmers®, look through Kraft Lake when Farmers isn’t the fit, and keep the FAIR Plan as the last resort.
A non-renewal letter is stressful, and it’s often about an insurer’s appetite, not you. We start with Farmers. When Farmers isn’t the best fit, we can also quote other companies through Kraft Lake Insurance Agency. If the regular market won’t write the home, the Missouri FAIR Plan, officially the Missouri Property Insurance Placement Facility, provides property coverage to people who haven’t been able to get it elsewhere. Its toll-free number is 800-392-7240, and applications have to be completed by a Missouri licensed agent.
For questions or a complaint about an insurer, DCI’s consumer hotline is 800-726-7390.
How does our Sullivan office quote a home?
The short answer: We start from your declarations page and the house itself, explain each coverage, and you pick the limits.
- Your declarations page
Your current limits, deductibles (including any wind and hail percentage) and endorsements. Every change from it is on purpose.
- The basics of the house
Year built, square footage, construction and the years of any electrical, plumbing or heating updates.
- Your roof
The year it went on and the material.
- What’s out back
Detached garage, shop, barn or well house, with rough sizes.
- Claims and your lender
Any recent claims, plus your mortgage company’s information. Then look up your flood zone.
Then call Tina or Matthew at (573) 358-4513, Monday through Friday from 9 AM to 5 PM Central, or stop by 878 Dunsford Dr. We actually explain the coverages to you and let you pick what works for you. If you have cars too, we’ll show you whether bundling makes sense; our Sullivan car insurance guide covers the auto side.
The bottom line on home insurance in Sullivan
Insure to rebuild cost, know your wind and hail deductible in dollars, count every building and decide on flood before the river does.
Call us at (573) 358-4513 or stop by 878 Dunsford Dr with your declarations page. You can also start on our home insurance page, visit our Sullivan office page or go straight to a free home quote.
By clicking Get My Free Quote, I give Tina Gregory Agency (Tina Gregory Insurance Agency LLC) and its licensed agents, and, for quotes from insurance companies other than Farmers, Kraft Lake Insurance Agency, my prior express written consent, by electronic signature, to contact me with calls and text messages — including marketing calls and texts made using automated technology or an artificial or prerecorded voice — and by email, at the number and email I provided, about my insurance quote and related insurance products and services, even if my number is on a Do Not Call list. My information is never sold or shared with other agencies for their own marketing. Consent is not a condition of purchase; I can call (573) 358-4513 instead. Message frequency varies. Message and data rates may apply. Reply STOP to opt out, HELP for help. I agree to the Privacy Policy and Terms of Use, including the arbitration clause and E-SIGN consent.
Sullivan home insurance FAQ
Does homeowners insurance cover flooding in Sullivan, MO?
No. Standard homeowners policies exclude flood, including rising water from the Meramec, the Bourbeuse or a local creek. Flood coverage is a separate policy, usually through the National Flood Insurance Program, and FEMA says a new policy has a 30-day waiting period, with limited exceptions. Sullivan participates in the NFIP, and private flood may also be available. Water backing up through a drain is different: that needs a water backup endorsement on your home policy.
Is Sullivan in the National Flood Insurance Program?
Yes. FEMA’s Community Status Book lists the City of Sullivan, community number 290136 in Crawford and Franklin counties, as participating in the NFIP’s regular program since June 15, 1981, with no sanction, and its current flood map is dated October 18, 2011. That means NFIP flood policies are available for homes in the city. To see your flood zone, search your address on FEMA’s Flood Map Service Center at msc.fema.gov, or call us and we’ll look it up with you.
How much does home insurance cost in Sullivan, MO?
There isn’t a reliable public average for Sullivan alone, and two homes on the same road can price very differently. Your price depends on what it would cost to rebuild the house, the roof, the home’s age and updates, the fire protection at your address, your claims history and the deductibles and add-ons you choose. Discounts such as bundling may apply; eligibility varies. The way to get a real number is a quote for your house.
Is sinkhole damage covered on a Sullivan-area home policy?
Usually not by a standard policy, which typically excludes earth movement. Sinkhole coverage may be available as an endorsement, depending on the company. The Missouri Department of Commerce and Insurance announced in March 2015 that Missourians can buy a standalone Sinkhole Loss policy through the Missouri FAIR Plan to supplement their primary coverage. Ask us what’s available for your address.
What do I need to get a home insurance quote in Sullivan?
Your declarations page if you have one, the home’s year built, square footage and construction, the roof’s age and material, the years of any major updates, a list of outbuildings, recent claims and your mortgage company. Call Tina or Matthew at (573) 358-4513, Monday through Friday from 9 AM to 5 PM Central, or start a free quote online. We’ll explain each coverage and you pick what works for you.
Last reviewed by Tina Gregory on .